By Michael Lanning October 4, 2026
If you suspect a wrong merchant category code higher fees problem, first get the four-digit MCC on your MID confirmed in writing by your processor or acquirer. Compare it with current Visa and Mastercard definitions, document your actual business activity, request a supported correction, and verify subsequent transactions at the interchange-program level rather than relying only on your monthly effective rate.
The practical response to a wrong merchant category code higher fees concern is an audit, not an immediate demand for a cheaper code. Confirm the classification actually being submitted, determine whether it conflicts with your principal business activity, and then determine whether the cost difference is truly caused by MCC.
That last step matters. An expensive transaction can result from the card product, card-present versus card-not-present handling, authorization and clearing data, settlement timing, regulated-debit status, missing enhanced data, or processor markup even when the MCC is completely correct.
For that reason, your action plan should be: identify the current MCC, compare it with official network definitions, review transaction-level interchange qualification, submit evidence to the acquiring side if the classification is wrong, obtain an effective date, and then test transactions processed after the correction.
wrong merchant category code higher fees: What to Check First
A wrong merchant category code higher fees investigation is justified when the merchant classification itself appears inconsistent with what the business principally sells or provides. It is not justified merely because this month’s processing statement costs more than last month’s.
Visa’s April 2026 Merchant Data Standards Manual defines MCC as a four-digit number used to describe a merchant’s primary business, generally based on annual sales volume, and explicitly says acquirers and their agents must assign the correct MCC.
Mastercard’s June 2026 merchant booklet likewise requires the acquirer to provide a valid and accurate MCC and defines an accurate MCC as one that most reasonably and fairly describes the merchant’s primary business.
That creates several legitimate reasons to investigate an account:
- The processor confirms an MCC that clearly describes another industry.
- The merchant profile or underwriting record shows the wrong business type.
- A category-specific interchange program appears unavailable.
- Transactions are being subjected to unexpected category-based network treatment.
- The MCC reported for applicable payment-card Form 1099-K reporting appears inconsistent with the business.
- Customer rewards categorization repeatedly reflects a materially different merchant category.
- Risk or acceptance controls appear to be tied to an industry classification that does not match the actual operation.
Quick Diagnosis
| Symptom | Could MCC Be Involved? | Also Check |
| Unexpected interchange category | Yes | Card product, qualification criteria, transaction method |
| Higher effective processing cost | Possibly | Processor markup, assessments, card mix, downgrades |
| Unexpected card decline | Sometimes | Issuer controls, fraud rules, card restrictions |
| Customer rewards category differs | Possibly | Issuer-specific rewards rules |
| Form 1099-K MCC appears wrong | Yes | Acquirer/PSE merchant record |
| Entire industry classification is wrong | Strong reason to investigate | Merchant application and underwriting file |
| Commercial-card costs increased | Possibly | Enhanced data, card product, Level II/III qualification |
| Online transactions cost more | Not necessarily | CNP qualification, authentication, card mix |
Do not start by asking, “Which MCC is cheapest?” Start by asking, “Which MCC does the network definition say accurately describes this business?”
What Is an MCC and Who Assigns It?
An MCC is normally a four-digit payment-card classification. Visa’s current manual says the classification should, in most cases, reflect the merchant’s primary type of business. Mastercard similarly requires the code to reasonably and fairly describe the merchant’s primary business.
Visa’s Merchant Data Standards Manual requires acquirers and their agents to assign the correct MCC and generally use the code that most accurately describes the merchant’s primary business.
For a merchant with more than one qualifying line of business, Visa’s current rules allow either the MCC representing the highest-sales-volume business or different MCCs for the separate lines of business, depending on the structure.
The current Visa manual is especially useful because it assigns responsibility to the acquirer and its agents, not to the merchant acting alone. Visa also reserves the right to require correction of incorrect MCC assignments.
The roles around the account can nevertheless be confusing.
An acquirer or acquiring bank is the financial institution responsible for providing or sponsoring card acceptance. A processor may operate the transaction platform and maintain merchant records for that acquiring relationship.
An ISO/MSP may sell or service the account. A payment facilitator may sponsor submerchants. A gateway mainly passes transaction information and may expose an industry or MCC configuration field.
That is why a gateway screen is not, by itself, proof of the network-facing MCC. For a correction audit, the processor/acquirer’s written merchant-profile confirmation is the stronger operational evidence.
Mastercard also draws an important pricing distinction: interchange is only one component of the merchant discount rate, and Mastercard itself is not involved in the acquirer’s merchant-pricing agreement.
How to Check My MCC Code on an Existing Merchant Account
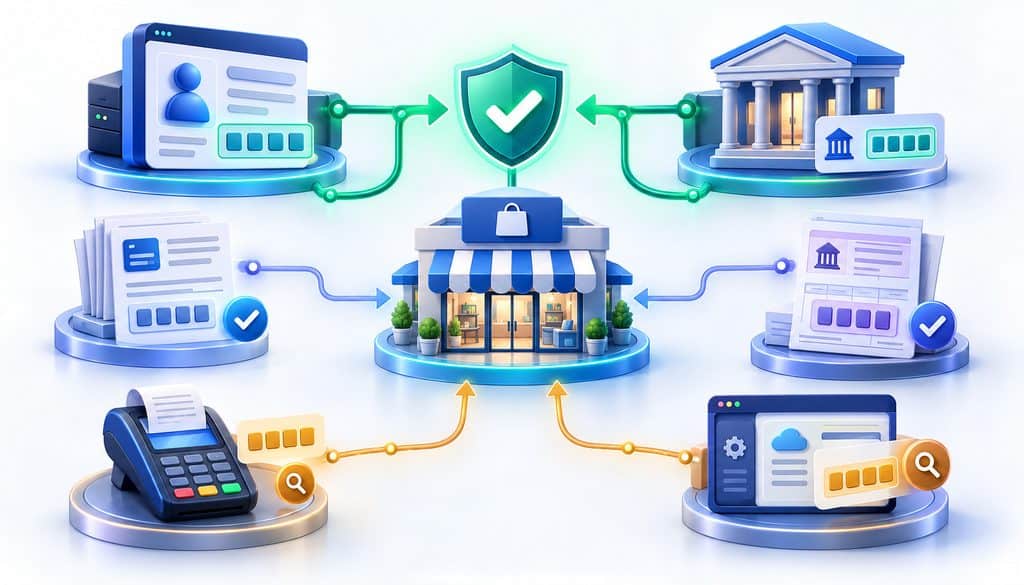
If your question is “how do I check my MCC code?”, do not rely on a public MCC search tool that guesses from your company name. You need the code actually attached to the merchant account.
1. Ask the processor or acquirer in writing
The strongest first request is:
“Please confirm the four-digit Merchant Category Code currently registered for MID [MID] and used for network transaction processing.”
Ask for a response through a secure support ticket, merchant portal, account-management email, merchant-account maintenance team, or underwriting team.
When merchants ask check my MCC code, this direct confirmation matters because the relevant issue is not what code an internet directory thinks your company should have. It is what code the acquiring side is actually using.
2. Review your processing statement and merchant profile
Some providers print an MCC, SIC/MCC field, merchant type, or industry description on the processing statement. Others do not.
Before treating a higher fee line as evidence that the MCC is wrong, audit the merchant statement line by line to separate interchange, network-related charges, processor markup, account fees, and changes in transaction mix.
That makes it easier to determine whether the cost increase is actually tied to merchant classification or to another pricing factor.
3. Review Form 1099-K when applicable
The IRS’s current posted Form 1099-K instructions say Box 2 is used for the four-digit MCC that the payment-card industry uses to classify the payee for the payment-card transactions on that form.
The instructions also make an important distinction: if the filer is a TPSO or does not use an industry classification system for its payees, Box 2 generally should not be completed.
So a Form 1099-K can provide useful corroborating evidence, but it should not replace direct processor/acquirer confirmation.
4. Treat receipt information cautiously
Do not assume a standard consumer receipt must print the four-digit MCC. A terminal or receipt configuration may contain category-related information, but absence of the MCC is not evidence that the account lacks one.
5. Treat a gateway field as supporting—not conclusive—evidence
Some gateways and virtual terminals expose an “industry,” “vertical,” “merchant category,” or MCC setting. That value may represent application configuration rather than the complete acquiring record.
To check my MCC code verification, obtain the acquirer’s or processor’s answer in writing.
How MCC Affects Processing Costs and Interchange
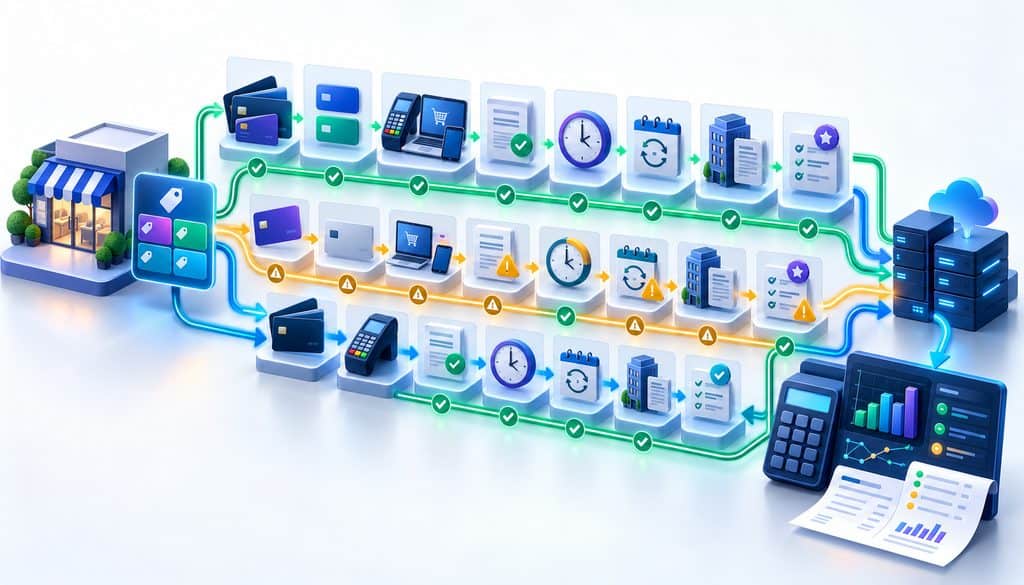
A wrong merchant category code higher fees concern is plausible because MCC affects processing costs, but there is an important limit: MCC does not independently determine the final interchange rate for every transaction.
Mastercard’s current U.S. interchange guidance makes the same distinction at the qualification level: merchant category can matter, but so can authorization-to-clearing timing, transaction data, enhanced data, and merchant sales or transaction volume. All applicable requirements for a particular interchange program must be satisfied.
Mastercard states this directly in its current U.S. interchange guidance. Its interchange programs have multiple qualification criteria, which can include merchant category, the interval between authorization and clearing, transaction data, enhanced transaction data, and merchant sales or transaction volume. All relevant requirements must be satisfied for the applicable program.
Visa’s published tables likewise show that the resulting interchange treatment varies by card/product type, transaction type, debit status, category and other program conditions. Its April 18, 2026 schedule distinguishes regulated and exempt debit, card-present and card-not-present transactions, and numerous category-specific programs.
So when someone says MCC affects processing costs, the technically accurate interpretation is that the classification can affect eligibility and routing into relevant interchange programs, not that an MCC creates one permanent rate for every card.
What can affect interchange besides MCC?
Depending on the network and program, qualification can also involve:
- Credit versus debit.
- Regulated versus exempt debit.
- Card product.
- Card-present versus card-not-present handling.
- Authorization information.
- Clearing/settlement timing.
- Authentication or transaction indicators.
- Transaction size.
- Enhanced commercial-card data.
- Merchant volume or program tiers.
- Other network-specific qualification requirements.
Commercial-card transactions need an additional qualification check before the MCC is blamed. Review whether Level II or Level III transaction data is being submitted correctly, because missing enhanced data can affect interchange qualification even when the merchant category itself is accurate.
Verified Example: Charitable Organizations
Category-specific programs demonstrate why merchant category code interchange rates need to be discussed carefully.
Visa’s April 2026 Merchant Data Standards Manual defines MCC 8398 as “Charitable Social Service Organizations” and MCC 8661 as “Religious Organizations.” The definitions are narrower than simply being a business that donates to charity or has nonprofit customers.
Visa’s current U.S. consumer-credit schedule, effective April 18, 2026, lists a Charity 1 card-not-present interchange program at 1.35% + $0.05 across the product columns shown in that table.
That does not mean an ordinary merchant can switch its MCC to 8398 or 8661 to obtain that rate; it must genuinely fit the classification and satisfy applicable program requirements.
Mastercard’s schedule is different. Its U.S. consumer-credit schedule effective April 17, 2026 lists Charities at 2.00% + $0.10 across the displayed consumer-credit products, while its unregulated consumer debit/prepaid schedule lists Charities at 1.45% + $0.15.
That difference alone shows why writing “MCC 8398 costs X%” would be inaccurate.
Verified Example: Utilities
Utilities provide another clear example of why MCC affects processing costs without making MCC the only qualification factor.
Visa defines MCC 4900 for electric, gas, water, sanitary and similar utility services. The definition covers genuine ongoing generation, transmission, distribution, water-supply and refuse-related utility activity.
Visa’s current U.S. schedule includes a card-not-present CPS/Utility consumer-credit program of $0.75 and separate debit utility programs; for exempt Visa consumer debit, for example, the schedule lists CPS/Utility at $0.65 and CPS/Utility Recurring Bill Payment at $0.45, while regulated debit follows the regulated debit structure shown in the schedule.
Mastercard’s June 2026 booklet similarly defines MCC 4900 for ongoing electricity, gas, heating oil, water and refuse-service activity. Its April 17 U.S. interchange schedule lists Utilities at $0.75 for the displayed consumer-credit products and $0.65 for unregulated consumer debit/prepaid.
Again, those are network- and product-specific programs. They do not support assigning MCC 4900 to a business that merely sells utility-related products.
Example — How a Wrong MCC Can Increase Transaction Cost
A wrong merchant category code higher fees situation becomes financially meaningful only when the incorrectly classified transactions would otherwise satisfy a different interchange program.
Suppose an organization processes $100,000 of qualifying card volume per month. Transaction-level analysis establishes that, for its actual card mix and transaction conditions, the correct classification would have generated a weighted average interchange cost 35 basis points lower than the classification used.
The illustrative difference is:
$100,000 × 0.0035 = $350 per month
That is not a universal MCC saving and should not be presented as one. The correct calculation uses the merchant’s real transactions and compares what each transaction actually qualified for against what it would have qualified for under the corrected merchant profile.
MCC Versus Interchange Downgrade — Do Not Confuse the Two
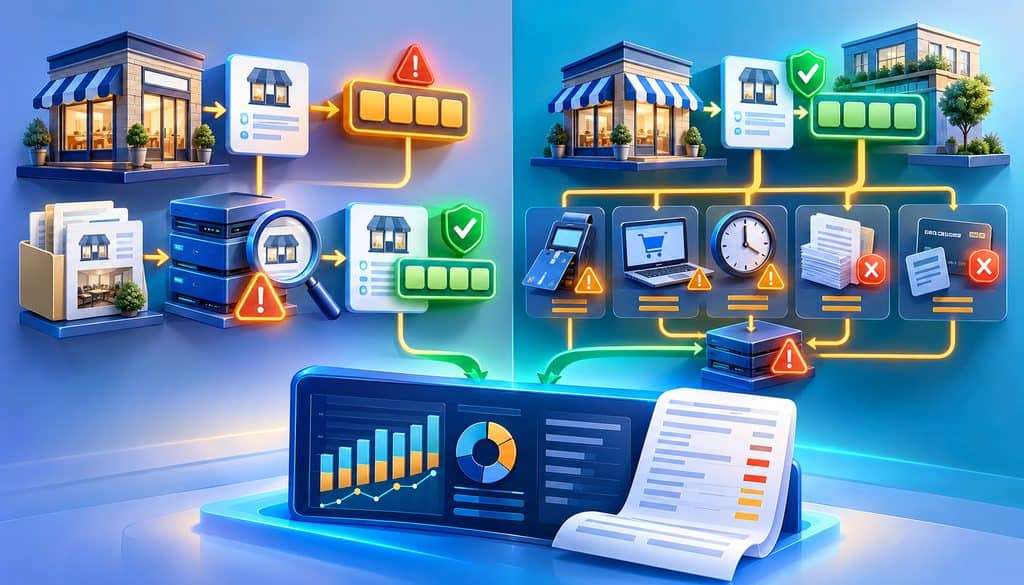
Merchants regularly diagnose an MCC problem when the real problem is interchange qualification.
| Issue | MCC Problem? | Qualification/Pricing Problem? |
| Business classified under wrong industry | Yes | Not primarily |
| Authorization cleared too late | No | Often |
| Missing required transaction data | Usually no | Potentially |
| Wrong transaction indicator | Usually no | Yes |
| Category-specific program unavailable | Possibly | Possibly |
| Processor markup is excessive | No | Yes, but not interchange qualification |
| Card-present sale treated as CNP | Usually no | Yes |
| Commercial enhanced data omitted | No | Potentially |
| Different premium-card mix | No | Yes, as a cost-mix issue |
This is also why merchant category code interchange rates should never be compared without controlling for product and qualification.
Mastercard explicitly says interchange is only one component of merchant pricing and that the acquirer establishes its merchant discount rate.
If the account uses interchange-plus pricing, separate the underlying interchange from the processor’s markup before estimating what an MCC correction could actually change. A higher total processing cost does not prove that the additional expense came from interchange.
The Other Consequences of an Incorrect MCC
Card acceptance and spending controls
MCC can be relevant to cardholder or issuer controls. Corporate-card and purchasing-card programs may restrict spending by merchant category, and network or issuer controls can use merchant categorization as one of their inputs.
Do not infer from that that every decline is an MCC issue. Available credit, issuer fraud systems, transaction characteristics, account restrictions and other controls may produce the same symptom.
Cardholder rewards
An incorrect MCC can sometimes affect how an issuer categorizes purchases for rewards.
For example, Chase’s current rewards-category explanation says merchants are assigned merchant codes based on the goods and services they primarily sell, and Chase groups those codes into rewards categories. It also warns that a merchant may appear to fit a rewards category but fail to qualify when its merchant code falls outside that category.
American Express likewise says additional-points qualification is determined using merchant codes and that a merchant is typically coded according to what it primarily sells.
A merchant therefore should not promise customers that an MCC correction will retroactively restore rewards. Rewards remain an issuer decision.
Form 1099-K classification
The IRS’s current instructions say Box 2 reports the four-digit MCC used to classify the payee for payment-card transactions. They also say that if receipts are classified under more than one MCC, the filer may issue separate Forms 1099-K or one form using the MCC corresponding to the largest portion of gross receipts.
The IRS Instructions for Form 1099-K say Box 2 is used for the four-digit MCC that classifies the payee for payment-card transactions reported on the form.
If a payee has receipts classified under more than one MCC, the filer may issue separate Forms 1099-K or use one form with the MCC corresponding to the largest portion of total gross receipts. A TPSO, or a filer that does not use an industry classification system for its payees, generally should not complete Box 2.
Do not confuse that reporting provision with card-network registration.
MCC is also not the same as:
- EIN or TIN.
- Federal tax classification.
- NAICS code.
- SIC in every context.
- Gross payment amount.
- Income-tax liability.
A wrong MCC on a Form 1099-K therefore does not automatically mean the reported gross amount or taxpayer-identification information is incorrect.
When Your Current MCC May Actually Be Correct
Before escalating a wrong merchant category code higher fees complaint, test whether the existing code is actually consistent with the network’s mixed-business rules.
Visa says that when a merchant has more than one line of business and could qualify for multiple MCCs, it generally may use the MCC describing the line with the highest sales volume for all Visa sales or use different MCCs for each line of business.
Visa also says different businesses on the same premises require their own MCC in specified circumstances, such as having different merchant names, distinct operating areas or separate points of sale.
Visa’s optional multiple-MCC guidance further says that a merchant with multiple product or business lines generally uses the classification corresponding to its highest-sales-volume business unless the acquirer and merchant determine additional merchant identifiers and MCCs are appropriate. Visa recommends periodic review of MCC assignments for accuracy.
That means a veterinarian selling pet food, a restaurant selling merchandise, a hotel operating a restaurant, or a medical practice selling wellness products cannot assume the retail side must receive its own MCC simply because that code has more attractive merchant category code interchange rates.
The transaction structure and principal activity matter.
What If My Business Fits Two Merchant Category Codes?
Visa provides more explicit public multiple-MCC rules than Mastercard’s general “primary business” standard, so those rules should not be blended into one universal statement.
Possible legitimate structures include one principal MCC covering the dominant activity, separate MCCs for genuinely separate business lines, separate merchant locations or acceptance points, or multiple MIDs where the acquirer determines that the structure is appropriate.
Visa even identifies cases where multiple MCCs are mandatory. For example, automated fuel dispenser transactions use MCC 5542 while other goods or services at the location use the appropriate classification for those transactions.
Mastercard’s public standard, by comparison, requires an accurate MCC that most reasonably and fairly describes the merchant’s primary business.
Do not turn the IRS’s multiple-MCC Form 1099-K reporting rule into a card-routing strategy. Tax-reporting flexibility does not authorize selectively routing sales through lower-cost classifications.
How to Submit an MCC Correction Request
A good MCC correction request is built around proof of business activity, not a spreadsheet showing which MCC looks cheapest.
For a wrong merchant category code higher fees case, use this workflow.
Step 1 — Establish the account record
Collect:
- MID.
- Current MCC.
- Legal name.
- DBA.
- Merchant location.
- Business description on file.
- Processor.
- Acquirer/sponsor bank where known.
- Date the current classification was confirmed.
Step 2 — Identify the defensible MCC
Use current network documentation—not an SEO list—to compare the merchant’s real products and services against the classification definition.
Visa’s current primary reference is the Visa Merchant Data Standards Manual. The April 2026 edition contains the general MCC-assignment rules plus individual MCC definitions.
Mastercard’s current public reference is its Quick Reference Booklet — Merchant Edition, dated June 2, 2026.
Step 3 — Build the evidence package
Useful evidence can include the website, invoices, contracts, product or service menu, business licenses, professional licenses, DBA documents, original merchant application, POS reports and a sales-mix report.
For a specialized classification, include specialized proof. A charity classification should be supported by documents showing the actual organization and activity. A claimed utility classification should be supported by evidence that the merchant really performs the activity described under MCC 4900.
Step 4 — Submit the MCC correction request
Suggested wording:
“Please open a merchant-category review for MID [MID]. The account currently shows MCC [current code]. Based on our principal business activity and the attached documentation, we believe MCC [proposed code] more accurately reflects the business. Please confirm the reviewing department, whether underwriting or acquiring-bank approval is required, the final MCC approved for the account, and its effective date.”
Step 5 — Ask who owns the decision
Frontline support may create the ticket, but the actual MCC reclassification processor workflow may involve merchant-account maintenance, underwriting, acquiring operations, compliance, risk or a sponsor bank.
Department names vary, so do not insist that every processor has an “MCC department.”
When MCC Reclassification Requires Re-Underwriting or a New MID
An MCC reclassification processor request is not always a harmless profile-field edit.
If the proposed classification shows that the business is materially different from what the acquirer originally approved, the acquirer may need to reassess the account. That can happen when products, fulfillment model, recurring billing, future-delivery exposure, transaction channel or regulated/restricted activity changes materially.
The outcome depends on the acquiring relationship. It may mean additional documentation, revised pricing or reserves, network-registration work where applicable, sponsor-bank review, or a different MID structure.
It does not follow that every legitimate correction requires a new MID.
If the proposed MCC reflects a materially different product line, sales channel, fulfillment model, transaction profile, or business activity, the acquirer may revisit the same merchant-account underwriting factors used during approval. That review can require updated business documents without necessarily requiring a completely new MID.
What If the Wrong MCC Is a Higher-Risk Category?
A wrong merchant category code higher fees issue involving a category perceived as higher risk needs three separate audits: interchange, processor pricing, and acquiring risk controls.
A processor may price, monitor or reserve an account differently based partly on its understanding of the business. But that commercial decision should not be presented as if Mastercard or Visa automatically charges every merchant in that MCC a “high-risk markup.”
Ask for the following in writing:
- Current MCC.
- Proposed corrected MCC.
- Effective date.
- Any processor-pricing change.
- Any reserve or settlement change.
- Any network-registration consequence.
- Whether previously processed transactions will be reviewed.
This separation prevents a merchant from mistaking processor risk pricing for interchange.
How to Escalate a Processor That Will Not Correct the MCC
If a documented wrong merchant category code higher fees problem remains unresolved, escalation should become more formal at each stage, not more aggressive.
Level 1 — Merchant support
Request a ticket number and written confirmation of the current MCC.
Level 2 — Account management or account maintenance
Ask for a formal merchant-profile review and provide the official network definition.
Level 3 — Underwriting/risk
Submit evidence showing what the business primarily sells and how transactions are generated.
Level 4 — Acquiring operations or sponsor bank
Ask which party has authority to approve and transmit the classification.
Level 5 — Written dispute
Document the current MCC, requested MCC, primary-source definition, supporting business records, date first reported, and the financial impact you are investigating.
Avoid unsupported threats about regulators. Jurisdiction over a merchant-acquiring dispute depends on the institution, contract and facts; there is no reason to assume a particular consumer regulator automatically handles a commercial acquiring classification dispute.
Can I Recover Interchange I Overpaid Because of the Wrong MCC?
A wrong merchant category code higher fees finding does not automatically create a right to a refund.
The first question is counterfactual: would those historical transactions actually have qualified differently if the correct MCC had been in place? That requires transaction-level analysis, not merely comparing the published rate attached to two category names.
Then ask:
- When was the incorrect classification first active?
- Who controlled the record?
- What did each affected transaction qualify for?
- What would it have qualified for under the corrected profile?
- What adjustment mechanisms or contractual remedies are available?
- What does the processor/acquirer say in writing about retrospective credits?
No current Visa, Mastercard or IRS source reviewed for this article establishes a general rule requiring every processor to retroactively reprice all past transactions after an MCC correction. Do not promise reimbursement that depends on facts and contractual or network-adjustment procedures not yet established.
How to Verify the MCC Fix Actually Worked
A wrong merchant category code higher fees case is not finished when support says “the code has been changed.” It is finished when the merchant can verify the account record and the treatment of new transactions.
1. Get written implementation details
Ask for the old MCC, corrected MCC, effective date and affected MIDs.
2. Process transactions after the effective date
Use subsequent transactions as the clean verification population.
3. Inspect transaction-level interchange
Where reporting permits, capture:
- Network.
- Card/product type.
- Transaction channel.
- Interchange program/category.
- Interchange rate.
- Per-item component.
- Interchange fee.
4. Compare to the network’s current schedule
For Visa transactions, compare to the applicable current Visa U.S. schedule. For Mastercard, compare with the applicable current U.S. program and its qualification requirements.
Do not compare the result only with an advertised processor rate.
5. Review the next statement
Control for volume, ticket size, card mix and transaction channel.
After the effective date, compare similar pre-correction and post-correction transactions while controlling for card mix, transaction channel, average ticket, and volume. Transaction-level interchange data is more reliable than comparing two monthly effective rates because the overall rate can move even when the MCC remains unchanged.
6. Check downstream records
Where applicable, monitor future merchant-profile information and payment-card Form 1099-K reporting.
A month-over-month effective-rate comparison alone is weak evidence. An increase in premium credit cards or card-not-present volume can mask a successful correction, while a favorable card mix can make an unsuccessful correction look cheaper.
Before-and-After MCC Audit Checklist
Before the change
- Confirm the current MCC in writing.
- Obtain the current Visa/Mastercard definition.
- Identify the principal business activity.
- Review actual interchange qualification.
- Separate processor markup from interchange.
- Gather supporting business records.
- Determine whether multiple genuine business lines exist.
During the MCC correction request
- Get a ticket/reference number.
- Identify the reviewing department.
- Submit the evidence package.
- Ask whether underwriting is required.
- Ask whether another MID is required.
- Obtain the approved MCC.
- Obtain the effective date.
After implementation
- Confirm the new MCC in writing.
- Process new transactions.
- Inspect transaction-level interchange.
- Compare like-for-like transactions.
- Review the next statement.
- Review applicable Form 1099-K information later.
- Request historical adjustment analysis if data supports it.
- Retain the entire correction file.
Common MCC Correction Mistakes
A wrong merchant category code higher fees audit often goes wrong because the merchant decides what the answer should be before checking the account.
Common mistakes include rate-shopping for an MCC, confusing MCC with NAICS or SIC, trusting a web lookup over the processor’s own record, blaming MCC for every high-cost transaction, overlooking missing Level II/III data, asking gateway support to change a classification controlled by the acquiring side, failing to get an effective date, and assuming prior transactions will automatically be refunded.
Another major mistake is comparing two effective rates without normalizing the card mix. An MCC correction can be valid even when the next month’s overall effective rate does not fall.
Frequently Asked Questions
How do I check my MCC code?
Ask the processor or acquiring bank to confirm in writing the four-digit MCC attached to your MID. A statement or Form 1099-K may provide supporting evidence, but the processor/acquirer’s current merchant record is the better operational starting point. Do not depend on a generic business-name MCC lookup.
Can the processor change my Merchant Category Code?
A merchant classification can be reviewed and corrected when the actual business supports another code. Visa places responsibility on acquirers and their agents for correct MCC assignment, while Mastercard requires acquirers to provide an accurate MCC describing the merchant’s primary business.
How long does an MCC correction take?
There is no reliable universal number of days in the primary network material reviewed here. Timing can depend on account maintenance, documentation, underwriting, acquirer review and whether the account structure must change. Ask for a case number, responsible team and expected effective date instead of publishing an invented turnaround time.
Does MCC affect interchange rates?
Yes, potentially. MCC affects processing costs because merchant category can be a qualification input and certain categories have specific network programs. But MCC is only one factor. Mastercard expressly lists other requirements, including authorization-to-clearing timing, transaction data and enhanced data.
Can the wrong MCC make my processing more expensive?
Yes, a wrong merchant category code higher fees problem can occur when the incorrect classification prevents otherwise-qualified transactions from receiving applicable category-specific treatment. But you must rule out card mix, processor markup, transaction qualification, regulated-debit status and other causes before calculating savings.
Can I choose any MCC that has cheaper interchange?
No. Visa says to select the MCC that most accurately describes the merchant’s business, generally reflecting its primary business. Mastercard requires a valid, accurate code that reasonably and fairly describes the merchant’s primary business.
Can one business have more than one MCC?
Sometimes. Visa expressly permits or requires multiple MCCs in defined circumstances and gives separate rules for multiple business lines, distinct businesses and certain transaction types.
Do not assume that means any merchant can split transactions between codes simply to obtain better merchant category code interchange rates. The underlying business structure and acquiring setup must support the classification.
Will changing my MCC change customer credit-card rewards?
Potentially for future purchases, because some issuers group merchant codes into rewards categories. Chase and American Express both describe using merchant classification in determining eligible rewards categories.
The issuer controls cardholder rewards, however. The merchant and acquiring processor cannot guarantee retroactive points or cash back.
Does my MCC appear on Form 1099-K?
For payment-card transactions, current IRS instructions say Box 2 reports the four-digit MCC used to classify the payee. A TPSO or filer that does not use an industry classification system generally does not complete that box. The IRS also provides options where receipts fall under more than one MCC.
Does the MCC reclassification processor team have to create a new MID?
No universal network rule says every correction requires a new MID. An MCC reclassification processor review may result in a simple profile correction or, when the business structure materially changes, additional underwriting or another account structure. The outcome depends on the acquirer and the actual business.
Final Takeaway: wrong merchant category code higher fees
When a merchant suspects a wrong merchant category code higher fees problem, the correct process is to prove the classification first and measure the cost impact second.
Confirm the MCC attached to the MID. Compare it against the current Visa and Mastercard definitions. Then separate classification from processor markup, card mix and interchange qualification before submitting the correction.
Build an evidence-based MCC correction request, obtain the final code and effective date in writing, and examine transactions processed afterward. The strongest proof is transaction-level interchange data matched to the current network schedule—not an assumption based on a headline rate.
If historical transactions genuinely would have qualified differently, request an adjustment analysis. If the transaction data does not show a difference, do not manufacture one simply because the new MCC sounds more favorable.