By Michael Lanning October 4, 2026
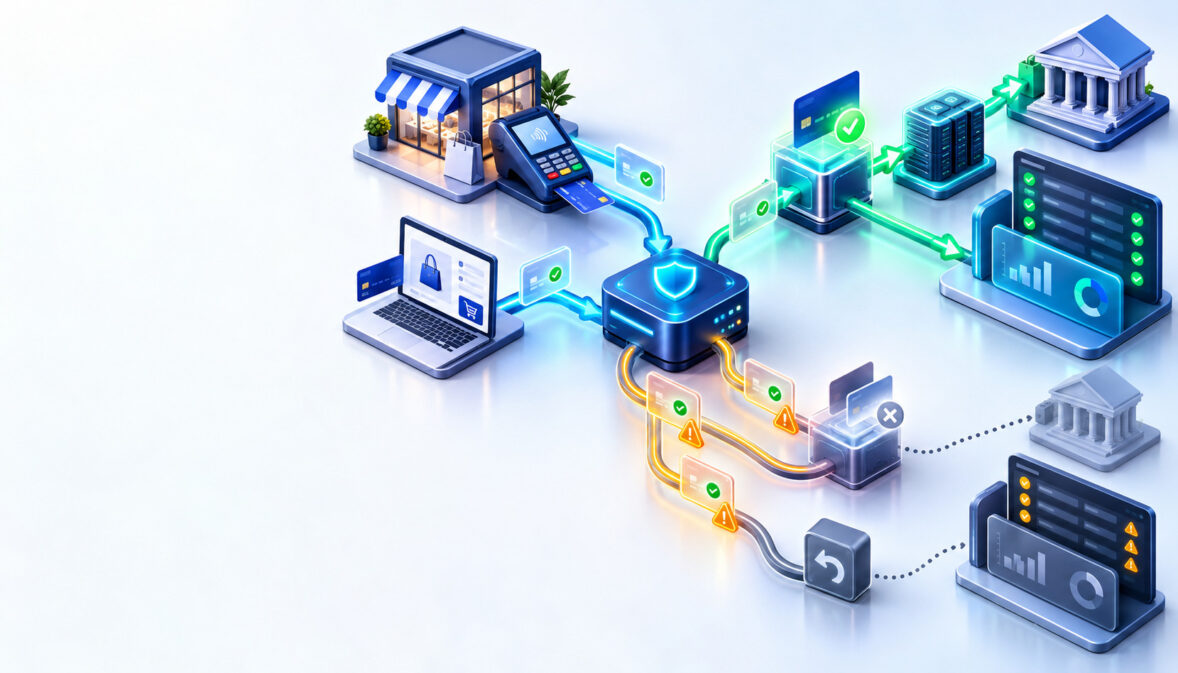
A misuse of authorization fee generally appears when an approved or partially approved authorization does not receive the lifecycle event expected for that transaction. The solution is to find the workflow creating orphaned authorizations and make sure completed transactions clear correctly while cancelled, abandoned, reduced, or failed transactions receive the appropriate reversal.
If this charge appears repeatedly on a processing statement, do not start by disputing the fee. Start by identifying the authorizations behind it.
The key question is simple: Which approved authorizations are entering your POS, gateway, or ecommerce system without a matching capture, clearing record, or authorization reversal?
Visa’s official authorization guidance describes its Misuse of Authorization System Fee as applying to approved or partially approved authorizations that cannot be matched to either a clearing transaction or an authorization reversal. Visa also warns that improperly handled authorizations can unnecessarily tie up cardholder funds.
That makes a recurring misuse of authorization fee primarily a transaction-lifecycle problem—not just a statement-pricing problem.
What the Misuse of Authorization Fee Actually Means
Authorization is the issuer’s approval for a proposed card transaction. Approval can temporarily reduce the cardholder’s available credit or available funds, but it is not the same as final settlement.
After an approval, the transaction should reach an explainable outcome. Depending on the situation, that may mean:
- the completed transaction is captured and cleared;
- an unused authorization is reversed;
- part of an authorized amount is reversed when the final amount is lower;
- an estimated authorization is completed through the applicable network-supported workflow;
- or another valid lifecycle event applies.
The problem occurs when the payment system effectively loses track of an approval.
For example:
Authorization approved → order cancelled → order record closed → no clearing → no reversal
The ecommerce platform may consider that transaction finished. The card network does not necessarily see it the same way.
Visa specifically states that its Misuse of Authorization System Fee can apply when an approved or partially approved authorization cannot be matched to clearing or an authorization reversal. Its official merchant material also identifies incorrect estimated/incremental authorization handling and certain inappropriate low-value test transactions as possible causes.
That is the operational meaning merchants should focus on when troubleshooting a misuse of authorization fee.
Visa Misuse of Authorization and Mastercard: What Is Verified
There is an important distinction between what the networks publicly document and what may appear on an individual processor statement.
Visa publicly identifies the Misuse of Authorization System Fee and explains its underlying trigger. The April 18, 2026 Visa Core Rules and Visa Product and Service Rules provide the current public Visa requirements governing authorization validity, estimated and incremental authorizations, reversals, transaction processing, and related lifecycle requirements.
The separate Visa Authorization and Reversal Processing Requirements for Merchants explains Visa’s processing-integrity fees in more operational language, including the Misuse of Authorization System Fee.
Mastercard also maintains authorization, preauthorization, final authorization, reversal, clearing, and lifecycle requirements. The latest publicly indexed Mastercard Transaction Processing Rules that I could independently verify for this review is dated June 10, 2025.
Mastercard updates its standards over time, so merchants troubleshooting a current Mastercard assessment should have their acquirer identify the precise current rule and fee event rather than assuming a processor statement label represents a universal Mastercard program.
| Network | What may appear on a statement | What to verify | Public fee amount used in this article? |
| Visa | Misuse of Authorization, Authorization Misuse, similar processor wording | Whether approved/partially approved auth lacked matching clearing or reversal | No exact amount stated because a current public unit amount was not verified |
| Mastercard | Processing Integrity, Auth Integrity, Network Integrity, or processor wording | Exact Mastercard rule/event and transaction population | No universal current amount stated |
| Processor/acquirer | Zero Floor Limit or proprietary descriptor | Network, rule, count, unit charge, and processor markup | Must be confirmed from the processor |
Do not copy a historical per-authorization fee from an old article or processor fee chart and present it as a current Visa or Mastercard rate.
If the statement shows a misuse of authorization fee, ask the processor for four things:
- the network that generated the assessment;
- the current network event or rule;
- the affected transaction count;
- the unit amount applied during that statement period.
This also helps separate genuine network assessments from processor-added charges.
What Does “Zero Floor Limit” Mean?
Visa currently defines a Floor Limit as a currency amount above which online authorization is required. That definition appears in the April 2026 Visa Core Rules.
However, the phrase Zero Floor Limit should not automatically be treated as the official current name of the Visa Misuse of Authorization System Fee.
Statement descriptors can be abbreviated, historical, processor-specific, or derived from internal billing systems.
If “Zero Floor Limit” appears on the merchant statement, ask:
Which current card-network rule does this descriptor map to, and which transactions generated the fee?
That answer is more useful than interpreting the label by itself.
Use This Diagnostic Table First
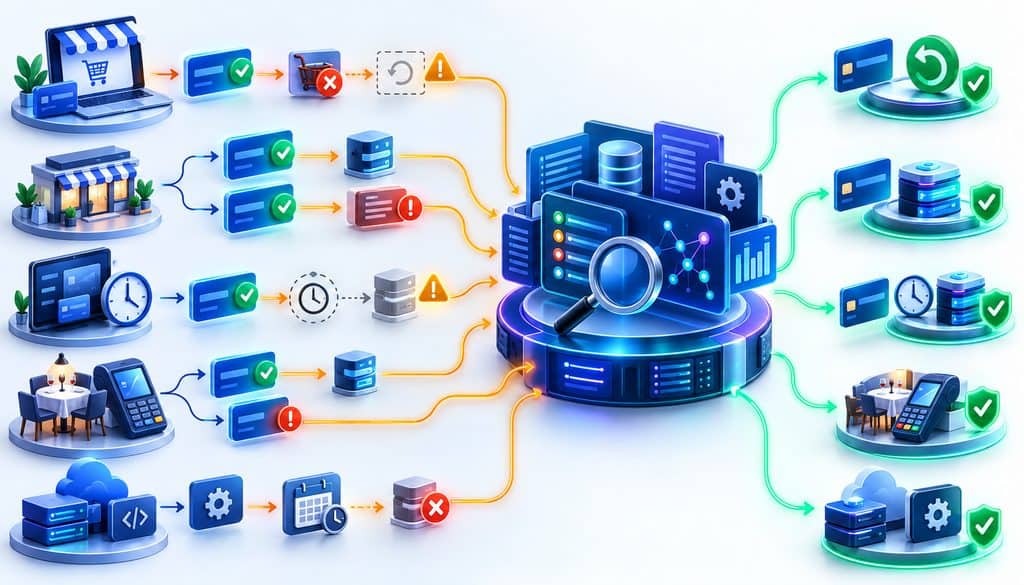
Before changing POS settings, group the affected transactions by pattern.
| Symptom | Most likely cause | What to inspect | Corrective direction |
| Authorization approved, order cancelled | Missing reversal | Ecommerce cancellation workflow | Send applicable reversal |
| Two auths, only one capture | Timeout or duplicate retry | Gateway/API logs | Resolve unused authorization |
| Auth-only orders keep aging | Capture process failure | Capture scheduler/order queue | Capture valid order or reverse it |
| Fees rise immediately after software update | Integration defect | Deployment and payment logs | Repair lifecycle logic |
| Restaurant transaction produces another unrelated auth after tip | Tip/adjustment configuration | POS transaction history | Correct gratuity/authorization workflow |
| Hotel/rental preauthorization remains after cancellation | Abandoned estimated auth | Reservation workflow | Reverse unused authorization |
| Numerous small approvals never settle | Card testing | Fraud and velocity logs | Stop testing activity and resolve approved tests |
| Clearing exists but cannot be matched correctly | Authorization/clearing linkage problem | Processor transaction identifiers | Correct lifecycle data |
| One channel produces nearly all exceptions | Channel-specific integration defect | POS/gateway/channel reports | Fix that workflow |
A pattern is more useful than a total dollar amount. Ten unexplained authorizations from ten unrelated causes require a different response than 500 identical exceptions from one broken ecommerce cancellation hook.
Workflows That Commonly Create Orphaned Authorizations
Abandoned Preauthorizations
Hotels, vehicle rentals, cruise merchants, restaurants, and some other businesses may legitimately authorize an estimated amount before the final transaction value is known.
Visa’s April 2026 rules permit estimated authorization requests when the final transaction amount is unknown, subject to specific conditions. They also permit incremental authorization requests after a valid estimated authorization when the original amount is no longer sufficient. An incremental request must use the required indicator and the same transaction identifier associated with the initial estimated authorization.
The problem appears when the underlying transaction ends but the authorization lifecycle does not.
For example:
Hotel deposit authorized → guest cancels → reservation closed → payment authorization left unresolved
A cancellation inside the reservation system does not itself prove that the network received an authorization reversal.
Businesses using deposits or estimated payment holds may also find the explanation of preauthorization charges on credit cards useful when separating a pending authorization from a completed charge.
If abandoned preauthorizations repeatedly remain unresolved, they can contribute to a misuse of authorization fee problem.
Ecommerce Auth-Only Orders Never Captured
Many ecommerce merchants authorize the card at checkout but delay capture until inventory is confirmed or goods ship.
That workflow is common. The failure occurs when the order changes status without the payment lifecycle changing with it.
Consider this sequence:
- Customer places the order.
- Gateway receives an approved authorization.
- Merchant waits to capture.
- Product becomes unavailable.
- Order is cancelled.
- Ecommerce system changes the order to “cancelled.”
- No authorization reversal is sent.
The merchant sees a closed order. The payment network may still see an unresolved approval.
Another common scenario is a failed capture scheduler. Approved orders accumulate because the automated capture job stopped running or a webhook stopped updating the fulfillment system.
This is one reason uncaptured authorizations cost more than the basic authorization request itself. Beyond a possible integrity assessment, they create reconciliation work, customer-service calls, duplicate pending transactions, and engineering time.
Reauthorizing Instead of Updating the Existing Lifecycle
Repeatedly creating new independent authorizations can leave earlier approvals unresolved.
Bad pattern:
Auth A → amount changes → Auth B → capture B → Auth A remains open
Where the applicable rules permit estimated and incremental authorization processing, the system should follow that lifecycle instead of creating unrelated authorizations.
Visa’s April 2026 rules also state that an incremental authorization does not extend the applicable transaction-processing timeframe.
That means developers should not assume that issuing an incremental authorization resets every clock associated with the original transaction.
Restaurant Tip and Final-Amount Problems
Restaurant authorization workflows are especially easy to misdiagnose.
An initial authorization and a different final settlement amount are not automatically evidence of a problem. Network rules contain specific provisions for gratuities, preauthorizations, final authorizations, and—in qualifying circumstances—incremental authorizations.
The defect to look for is an unrelated second approval that is created when the POS should be completing or updating the existing payment lifecycle.
For example:
Initial restaurant authorization → gratuity entered → POS creates unrelated Auth B → Auth B settles → original Auth A is never resolved
The merchant should ask the POS vendor exactly how the product handles initial authorization, gratuity, incremental authorization where applicable, and final capture.
Do not configure restaurant payment logic from a generic “tip tolerance” rule found online. Applicable treatment can depend on network, payment environment, authorization type, and transaction details.
Card Testing and Fraud Attempts
Card-testing attacks often create large volumes of declines, but declined authorization attempts are not the same problem as approved authorizations left without a lifecycle outcome.
Focus on the approved tests.
Visa’s authorization guidance specifically identifies the use of $1 test transactions in certain circumstances instead of the appropriate account-verification process as behavior that can lead to its processing-integrity fee.
Strong fraud controls therefore matter for authorization integrity as well as fraud loss.
Do not disable velocity controls simply to improve the auth to capture ratio. Doing so could improve one metric while making the underlying fraud problem much worse.
Duplicate Authorization After a Timeout
This is one of the clearest integration failures.
Authorization A sent
↓
Issuer approves it
↓
Application does not receive the response in time
↓
Application assumes failure
↓
Authorization B is sent
↓
B is approved and captured
↓
A remains unresolved
Visa’s April 2026 rules specifically require reversal when an approval response is received after a POS transaction timeout.
The engineering lesson is important:
A timeout means the transaction state may be unknown. It does not prove that no authorization occurred.
Applications should use the gateway’s supported status-retrieval, transaction-reference, or idempotency functionality instead of blindly issuing another financial authorization.
Cancelled Orders That Never Trigger a Payment Reversal
“Cancel order” and “reverse authorization” are not interchangeable commands.
An order can be cancelled in:
- a shopping cart;
- an order-management system;
- a restaurant POS;
- a hotel reservation platform;
- an ERP;
- a gateway;
- or a processor portal.
Only the payment action determines what happens to the authorization.
Ask the software provider:
When an approved transaction is cancelled before capture, what payment operation is sent, and does it reference the original authorization?
That question frequently reveals the source of a recurring misuse of authorization fee.
Capture, Reversal, Void, or Refund: Which Action Is Correct?
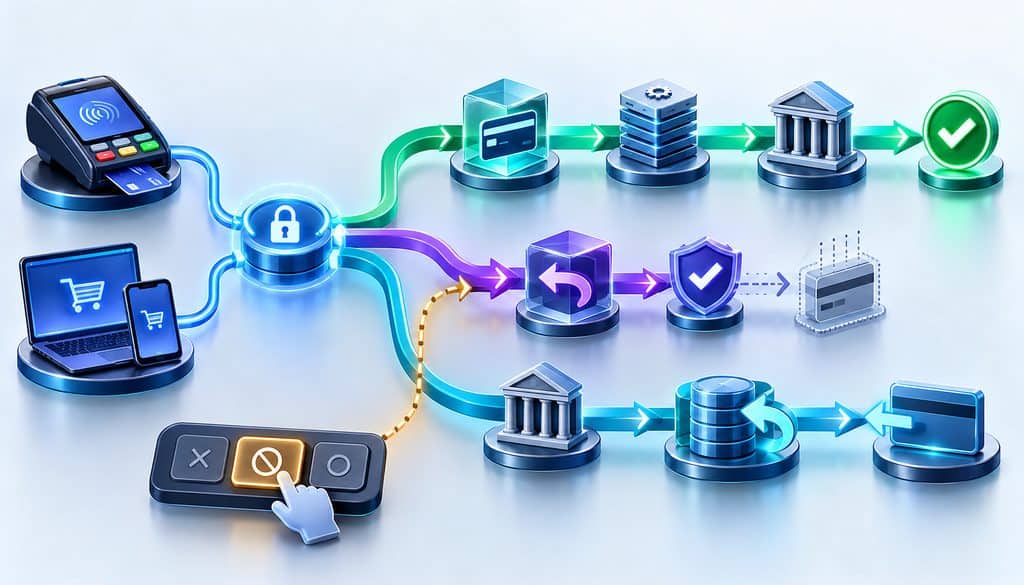
The basic decision is:
Authorization approved
↓
Will the transaction be completed?
↓
Yes → Capture and clear the transaction correctly
No → Send the applicable authorization reversal
Already settled and value must be returned?
↓
Refund
A refund is not the normal fix for an authorization that never settled.
Authorization Reversal vs Void vs Refund
The authorization reversal vs void distinction matters because “void” is usually a POS or gateway interface term rather than a complete description of the network message.
| Action | Appropriate situation | Has original sale settled? | Does settled money move? | What happens to the auth? |
| Authorization reversal | Approved transaction will not complete, or unused authorization must be released/reduced | No | No refund of settled funds | Cancels or reduces authorization |
| Void | Pre-settlement cancellation command | Usually no | Usually prevents completion | Depends on platform implementation |
| Refund | Money must be returned after settlement | Yes | Yes | Does not replace missing reversal |
Authorization Reversal
A reversal is the important lifecycle event when an approved transaction will not be completed or when an unused authorized amount must be released under the applicable rules.
Visa’s April 2026 public rules state that for an uncompleted transaction, the merchant must submit an authorization reversal within 24 hours of the earlier applicable trigger, including cancellation/payment by another means or the end of the approval-response validity period.
For a completed transaction whose final amount is lower than the sum of authorized amounts, the difference generally must be reversed within 24 hours of completion, subject to the stated network exceptions.
Void
A void might trigger the correct reversal behind the scenes.
Or it might simply remove an unsettled transaction from a local batch.
That is why authorization reversal vs void cannot be answered solely from the button label.
Ask:
Does the Void command transmit the applicable network reversal using the original authorization data?
Refund
A refund normally applies after the original payment has settled.
If an approved authorization never settled, refunding is generally not the appropriate substitute for a missing reversal.
Misconception: “Cancelling the sale in my POS automatically releases the authorization.”
Not necessarily. The POS may update only its own ticket or order record. Verify that the underlying payment integration actually sends the appropriate reversal.
How Long Can an Authorization Remain Open?
There is no single correct answer such as “all authorizations expire after seven days.”
Merchants need to distinguish at least five concepts:
| Timing concept | What it means |
| Issuer hold | How long available credit or funds may appear reduced |
| Authorization validity | How long the approval remains usable under applicable network rules |
| Processing/capture timeframe | How long the merchant has to process the transaction under the applicable rules |
| Reversal deadline | When an unused authorization or unused amount must be reversed |
| Gateway/batch timing | Operational settings inside the merchant’s payment system |
These clocks are related, but they are not interchangeable.
Visa Processing Timeframes
Visa’s official merchant authorization material summarizes the general maximum processing periods as follows, while explicitly directing merchants to the Visa Rules for country-specific requirements:
| Transaction type | General Visa timeframe described in current public material |
| Lodging, vehicle rental, cruise estimated authorization | 30 calendar days |
| Listed rental merchant categories | 10 calendar days |
| Cardholder-initiated card-absent transactions | 10 calendar days |
| Card-present transactions | 5 calendar days |
Visa’s Core Rules contain additional distinctions and country-specific requirements, so these figures should not be turned into a universal merchant rule.
Visa also states that incremental authorizations do not extend the underlying processing timeframe.
The practical lesson is to configure systems according to the merchant’s actual network, transaction type, authorization method, geography, and acquiring setup—not according to a blanket expiration number.
Mastercard Timing Requires the Same Caution
Mastercard’s public Transaction Processing Rules contain different concepts for preauthorization, final authorization, clearing, reversals, and authorization-related protection periods.
Do not convert one Mastercard timeframe into a statement that “Mastercard authorizations always expire after X days.”
For a current production configuration, have the acquirer or gateway identify the rule applicable to that specific payment environment.
That approach is both safer and more useful than publishing an oversimplified universal number.
How to Find the Fee on a Merchant Statement
A stale authorizations merchant statement investigation should begin with the exact descriptor and transaction quantity.
Look in:
- network or card-brand fees;
- pass-through assessments;
- authorization charges;
- miscellaneous fees;
- processor fee detail;
- transaction-detail reports;
- gateway exports.
Possible labels include:
- Misuse of Authorization;
- Authorization Misuse;
- Zero Floor Limit;
- Processing Integrity;
- Authorization Integrity;
- Auth Integrity;
- Network Integrity.
These descriptors are examples, not a universal naming standard.
If the statement itself is difficult to reconcile, a structured merchant statement audit can help separate transaction counts, authorization fees, card-network charges, processor fees, and account-level charges before the authorization investigation begins.
If the processor describes the charge as a pass-through network cost, compare it with how the account separates wholesale costs and provider margin. The explanation of interchange-plus pricing is relevant here because network fees and processor markup are distinct cost layers even when a statement displays them close together.
For a stale authorizations merchant statement review, the most important document is still the transaction-level exception report.
A summary fee line tells you what was charged.
The exception report tells you what needs to be fixed.
Estimate the Number of Affected Authorizations
If the statement already provides a transaction quantity, start there.
If it shows only a total misuse of authorization fee, ask the processor for the actual per-occurrence assessment used for that month.
Then calculate:
Estimated events = total verified charge ÷ verified unit charge
Do not use a unit amount copied from an old online fee chart.
For example, using explicitly hypothetical numbers:
- total integrity charge: $24;
- processor-confirmed hypothetical unit amount: $0.12;
- estimated events: 200.
The $0.12 figure above is an illustration only. It is not presented as a current Visa or Mastercard rate.
Use the Auth to Capture Ratio to Find Exceptions
Suppose the gateway reports:
| Monthly activity | Count |
| Approved authorizations | 4,850 |
| Completed captures | 4,690 |
| Documented reversals | 90 |
| Unexplained approvals | 70 |
Those 70 approvals should be investigated.
The auth to capture ratio is not a network compliance threshold. There is no universal perfect ratio because hotels, ecommerce businesses, restaurants, rentals, subscription merchants, and ordinary retail stores authorize transactions differently.
Use the auth to capture ratio as an exception signal.
The real question is whether the gap between approvals and completed lifecycle events can be explained.
When uncaptured authorizations cost money month after month, that unexplained population is where the investigation should begin.
Build a Monthly Authorization Reconciliation
A simple reconciliation file is often more useful than another statement review.
| Authorization | Order | Approved amount | Capture? | Reversal? | Final status | Action |
| A101 | 80101 | $125 | Yes | — | Completed | None |
| A102 | 80102 | $80 | No | Yes | Cancelled | None |
| A103 | 80103 | $49 | No | No | Unknown | Investigate |
| A104 | 80104 | $250 | Partial | Partial | Completed | Verify amount |
| A105 | 80105 | $65 | Yes | — | Duplicate approval also exists | Investigate duplicate |
Match whatever identifiers are available:
- authorization code;
- processor transaction ID;
- gateway reference ID;
- network lifecycle/reference identifier where available;
- order number;
- MID/location;
- amount;
- authorization timestamp;
- capture record;
- reversal record.
Terminology varies across processors.
The objective is not to force every provider into one naming convention. It is to preserve the relationship between the original authorization and the subsequent capture, reversal, or other lifecycle event.
POS and Gateway Settings to Check
If the misuse of authorization fee continues month after month, inspect functionality rather than searching for a setting literally named “Misuse of Authorization.”
Ask whether the system:
- sends a reversal when an approved order is cancelled;
- handles approved transactions that fail before capture;
- monitors aging auth-only orders;
- reverses unused amounts where required;
- supports estimated and incremental authorization correctly;
- handles restaurant gratuity without unnecessary duplicate approvals;
- prevents duplicate authorizations after timeouts;
- monitors scheduled capture jobs;
- alerts staff when captures fail;
- handles partial approvals correctly;
- retries failed webhooks safely;
- preserves the original transaction reference during reversals;
- prevents uncontrolled AVS/CVV retry loops;
- uses fraud velocity controls against card testing.
Different platforms use different names for these functions.
Ask the POS or gateway vendor what the system does, not what its setting is called.
API and Gateway Integration Bugs
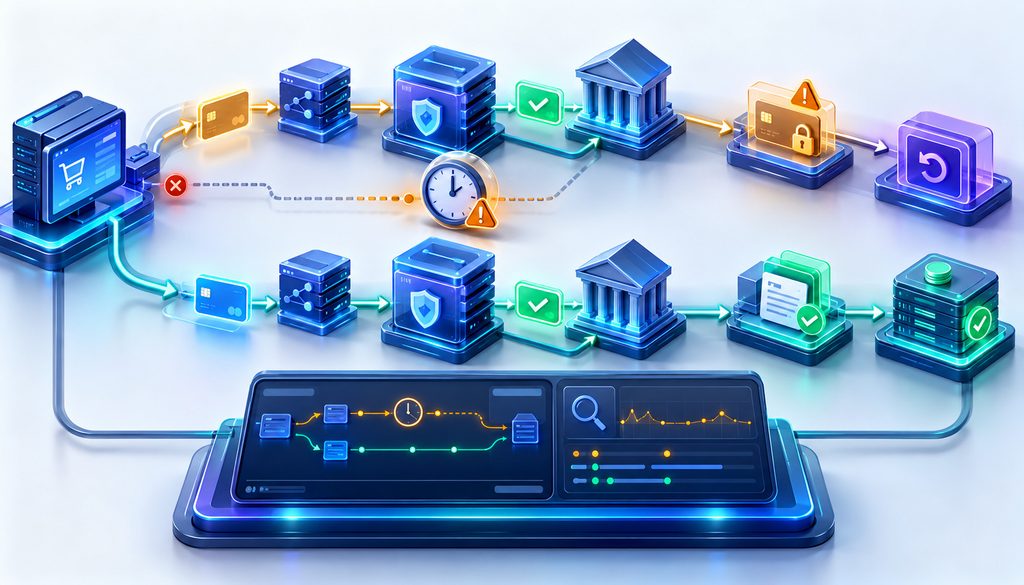
A sudden misuse of authorization fee increase after a deployment, gateway migration, API update, or checkout change should be treated as a possible software regression.
One common pattern is:
- Application sends authorization.
- Issuer approves it.
- Gateway response is delayed.
- Application times out.
- Software assumes the first authorization failed.
- New authorization is sent.
- Second authorization is captured.
- First approval remains unresolved.
The developer should pull:
- outbound API request;
- gateway request/reference ID;
- response timestamp;
- HTTP/API response;
- application timeout timestamp;
- authorization code;
- order ID;
- retry counter;
- capture call;
- reversal call;
- webhook history;
- deployment log.
Other defects include:
- capture jobs stopping;
- cancellation events not mapped to reversal APIs;
- stale webhooks;
- wrong transaction identifier used for the reversal;
- duplicate retry loops;
- reversing the wrong authorization;
- switching processors without updating payment-lifecycle logic.
If an integration returns an unknown or timeout state, do not automatically treat that state as a decline.
First determine whether the original request reached the processor and issuer.
When the Fee Signals an Integration Bug
Escalate technically when:
- integrity-event counts jump after a gateway migration;
- charges begin immediately after a software release;
- one MID or channel produces most exceptions;
- every cancelled ecommerce order leaves an unresolved approval;
- duplicate approvals cluster around timeout events;
- restaurant tip adjustments create two separate authorizations;
- capture failures correlate with API errors;
- the auth to capture ratio changes sharply without a change in business operations.
Start with the processor because it should be able to identify the network and affected transaction population.
Involve the gateway when payment lifecycle messages are missing or rejected.
Involve the POS vendor when the terminal or ticket workflow generates incorrect transactions.
Involve the developer when API logs reveal retries, missing cancellation hooks, duplicate requests, or failed capture processes.
What to Ask Processor Support
Use a request that produces evidence:
“I am seeing [statement descriptor] charges and need transaction-level detail for the authorizations that triggered them. Please provide the network, authorization date, authorization code or transaction identifier, amount, MID/location, applicable network fee or rule, and whether you received a corresponding clearing transaction or authorization reversal.”
Then ask:
- Which card network generated the assessment?
- What current rule or program triggered it?
- Which transaction IDs generated the charge?
- What was the applicable unit amount for this statement period?
- Was clearing expected but not received?
- Was a reversal expected but not received?
- Is the charge passed through directly or marked up?
- Can you provide the same exception report monthly?
- When did the exception count begin increasing?
- Did it coincide with a gateway, POS, or software change?
That changes the conversation from “Why is this fee on my bill?” to “Which payment workflow is failing?”
10-Step Troubleshooting Workflow
1. Record the exact descriptor
Write down the fee name, total, quantity, network if shown, and affected MID.
2. Confirm the network
Do not infer the network solely from a phrase such as Zero Floor Limit or Integrity Fee.
3. Confirm the unit assessment
Ask the processor for the amount applicable to the actual statement period.
4. Obtain transaction-level exceptions
The processor should identify the authorization events associated with the assessment.
5. Match approvals to captures
Remove successfully completed transactions from the exception population.
6. Match remaining approvals to reversals
Determine whether unused approvals were properly resolved.
7. Group the unresolved transactions
Typical groups are ecommerce cancellation, timeout retry, abandoned preauthorization, restaurant gratuity, card testing, capture failure, or another identifiable workflow.
8. Fix the payment lifecycle
Correct POS configuration, gateway settings, cancellation hooks, capture jobs, retry behavior, or API code.
9. Monitor daily
Do not wait until the next monthly statement to discover that the problem is continuing.
10. Reconcile the next statement
Compare approvals, captures, reversals, unresolved exceptions, and the new misuse of authorization fee count.
The goal is not a mathematically perfect authorization-to-capture percentage. The goal is an explainable lifecycle for every approved authorization.
Three Common Examples
Ecommerce Cancellation
- Problem: The order is authorized, then cancelled before shipment. The application marks the order cancelled but sends no payment reversal.
- What the network sees: Approved authorization without matching clearing or reversal.
- Correct fix: Connect the cancellation workflow to the applicable authorization-reversal operation using the original payment reference.
- Restaurant Tip Adjustment
- Problem: The POS authorizes the original check, then creates an unrelated second authorization when gratuity is added.
- What the network sees: Two approvals associated with one economic purchase, but only one is ultimately completed.
- Correct fix: Configure the POS to use the network-supported gratuity, estimated/incremental, and completion workflow applicable to that transaction.
Gateway Timeout
- Problem: Authorization A is approved, but the response arrives late. Software sends Authorization B and captures B.
- What the network sees: B has a lifecycle outcome; A remains unresolved.
- Correct fix: Use supported status/idempotency logic and reverse an unused duplicate approval instead of abandoning it.
These patterns explain why a recurring misuse of authorization fee usually cannot be solved from the statement alone.
What Not to Do
Do not ignore the charge because the individual amount looks small. A small event-based charge repeated hundreds or thousands of times can indicate a systematic payment defect.
Do not use refunds when nothing settled.
Do not repeatedly reauthorize a payment without resolving the earlier approved authorization.
Do not assume closing a ticket or cancelling an order automatically sends a reversal.
Do not use a blanket “all authorizations expire after seven days” rule.
Do not disable fraud controls simply to improve authorization metrics.
Do not force-capture an aging authorization without confirming that it is still valid under the applicable network and processor requirements.
And do not assume all uncaptured authorizations cost the same amount or create the same network outcome. Transaction type and lifecycle matter.
Merchant Cost and Cardholder Experience
Unresolved authorizations create problems on both sides of the transaction.
For merchants, they can contribute to:
- card-network or processor integrity charges;
- excess authorization activity;
- reconciliation exceptions;
- developer troubleshooting;
- payment-support tickets;
- harder month-end reconciliation.
For cardholders, unresolved authorizations can temporarily reduce available credit or funds and may appear as confusing pending transactions.
Duplicate approvals can be particularly frustrating because a cardholder may see two pending entries even when only one eventually settles.
That is why reducing a misuse of authorization fee is not just a pricing exercise. It improves transaction hygiene and customer experience at the same time.
Frequently Asked Questions
What is a misuse of authorization fee?
A misuse of authorization fee is associated with an approved authorization that does not receive the expected lifecycle outcome. Visa states that its Misuse of Authorization System Fee applies to approved and partially approved authorizations that cannot be matched to either clearing or an authorization reversal.
Why do I see Visa misuse of authorization fees on my statement?
A visa misuse of authorization issue generally indicates that some approved authorizations are not being matched correctly to clearing or reversal activity. Common causes include cancelled auth-only orders, abandoned preauthorizations, timeout duplicates, failed capture jobs, and incorrect estimated or incremental authorization handling.
Is a void the same as an authorization reversal?
Not necessarily. The authorization reversal vs void question depends on the gateway or POS implementation: a void may initiate the correct reversal, but another system may merely remove an item from an unsettled batch. Ask the provider what network-facing operation its Void command performs.
Does a refund remove a misuse-of-authorization problem?
A refund normally applies after a transaction has settled. It does not substitute for the authorization reversal that should have been sent when an approved transaction was abandoned before settlement.
How long can an authorization stay open?
There is no universal period. Timing depends on the card network, transaction type, authorization type, payment environment, geography, merchant category, and any applicable estimated, incremental, extended, or merchant-initiated transaction rules.
What does Zero Floor Limit mean on a statement?
Visa defines a floor limit as an amount above which online authorization is required. But a statement descriptor reading Zero Floor Limit should still be mapped by the processor to the current underlying network rule rather than assumed to be the official name of a particular fee.
How do I know whether my gateway is creating stale authorizations?
Compare approved authorizations with captures and reversals, then group the unexplained approvals by channel and error condition. A concentration around timeouts, cancellations, failed capture jobs, or a recent deployment strongly suggests a gateway or integration problem.
Stop the Misuse of Authorization Fee by Closing the Authorization Lifecycle
The long-term fix for a misuse of authorization fee is not simply asking for the charge to be removed. It is finding the transaction workflow that leaves approved authorizations without the appropriate outcome.
Completed transactions should move into capture and clearing. Approved transactions that will not be completed should receive the applicable authorization reversal. Unused portions of authorizations should be handled according to the relevant network requirements, while refunds belong to transactions that have already settled.
The most useful monthly control is straightforward:
Approved authorizations = completed captures + legitimate reversals + documented exceptions that can be explained.
If the numbers do not reconcile, investigate the gap.
Reconcile next month’s approvals, captures, reversals, duplicate authorizations, and unresolved exceptions against the statement’s misuse of authorization fee count. If the charge remains, repeat the analysis by sales channel until the workflow causing it is isolated.